How do I calculate my lease instalment?
Enter the price, deposit, term, residual value and interest rate. The calculator deducts the deposit and the discounted residual value from the price and spreads the rest, plus interest, over the months. With the example values, a three-year-old used car at the median price, that comes to around CHF 368 a month.
- Deposit and all instalments
- CHF 20’985
- Of which interest
- CHF 4’495
- Total if you buy at the residual value
- CHF 37’485
The example values come from the market: CHF 32’990 is the median price of used cars from 2023 in our analysis, calculated from 8’839 listings on 15.10.2026. Deposit, residual value and interest rate are examples. The law calculates the same way: the effective annual rate is based on the cash price, residual value and instalments (Art. 33 of the Consumer Credit Act, CCA).
How do I check the interest rate in a leasing quote?
Enter the price, deposit, term and residual value from the quote in the calculator, and the monthly instalment offered below them. The calculator finds the rate that produces exactly this instalment. If it differs markedly from the effective annual rate stated, ask what other costs are in the instalment.
What a lease with private individuals must contain is set out in Art. 11 CCA on leasing contracts. This includes the cash price, the number, amount and due dates of the instalments and any security deposit. Likewise any insurance required, the effective annual rate and a table for early termination. The contract is in writing, and you receive a copy.
How high can the leasing interest rate be in Switzerland?
For leases with private individuals, the maximum interest rate is 10 per cent effective per year. It is set by the Federal Department of Justice and Police in an ordinance, as of 1 January 2026. For overdrafts on an account or a credit card, the limit is 12 per cent.
The limit is set out in the Ordinance on the Maximum Interest Rate for Consumer Credit. It applies because the law treats a private lease as consumer credit if the instalments rise on early termination (Art. 1 para. 2 CCA).
Anyone leasing a car for their business is not a consumer within the meaning of the law (Art. 3 CCA). This limit does not apply to them. The calculator warns you as soon as the rate is above 10 per cent.
What does residual value mean in a lease?
The residual value is what the car is still worth at the end of the term according to the contract. A high residual value lowers the instalment because you pay off less. Taking the car over at the end only pays off if the residual value is below the market value the car has by then.
| Year | Price | Kilometres | Listings |
|---|---|---|---|
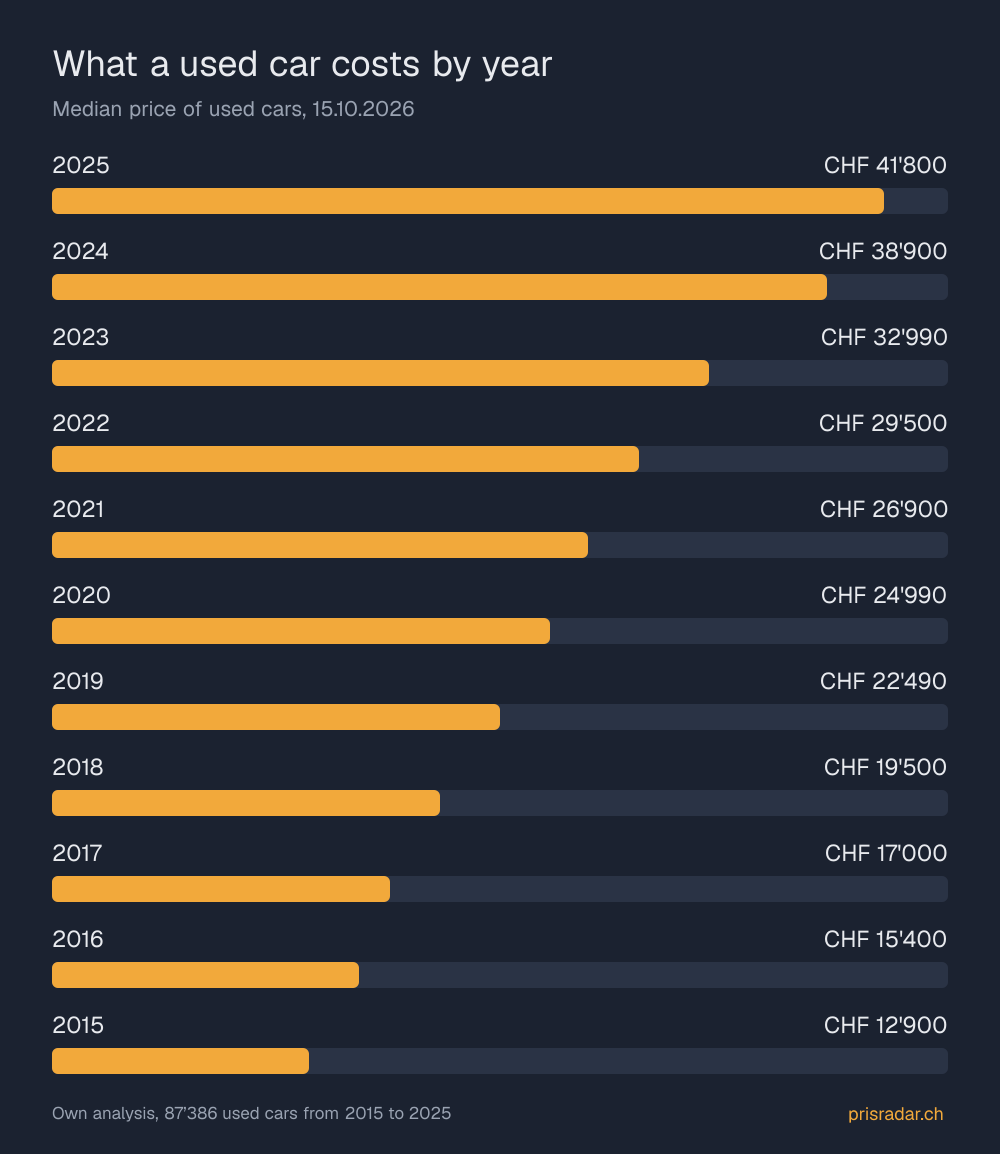
| 2023 | CHF 32’990 | 40’500 km | 8’839 |
| 2021 | CHF 26’900 | 72’711 km | 8’500 |
| 2019 | CHF 22’490 | 95’900 km | 8’203 |
These are different cars, not a single model, but the direction is clear. How to work out the residual value for your model is shown in the guide Calculating residual value.
Read in the contract who bears any gap between residual value and market value, and what excess mileage and damage cost when you return the car. Before you take the car over, it is worth looking at the leased car’s market value today.
Is a large deposit on a lease worth it?
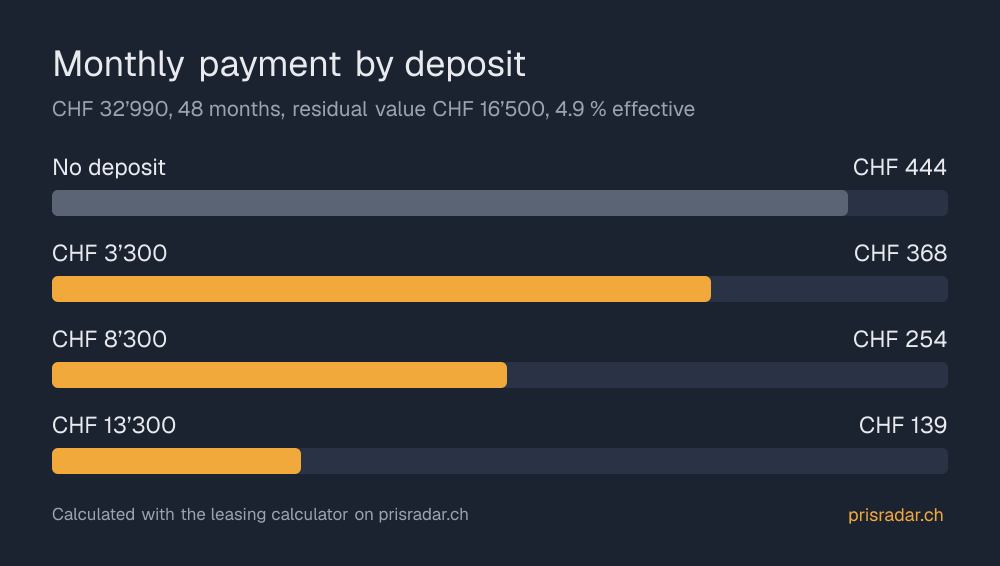
A deposit lowers the monthly instalment but only saves the interest on its own amount. With the example values, CHF 5’000 more deposit lowers the instalment from CHF 368 to CHF 254. But over four years, the interest costs only fall by CHF 505. In return, the money is tied up for the whole term.
Calculated with the calculator above: price CHF 32’990, term 48 months, residual value CHF 16’500 and 4.9 per cent interest. With a deposit of CHF 3’300 you pay CHF 4’495 in interest; with CHF 8’300 it is CHF 3’990. Whether that pays off depends on what the money would earn elsewhere. If the leasing company requires a security deposit, the contract must state it (Art. 11 para. 2 CCA).
Can I end a lease early?
Yes. Under the Consumer Credit Act, you can give 30 days’ notice to the end of any three-month period of the lease. What you then pay on top is set out in the table that every private lease must contain. You can also withdraw from the contract in writing within 14 days of receiving it.
Termination is governed by Art. 17 para. 3 CCA, withdrawal by Art. 16 CCA. The withdrawal period starts as soon as you have received a copy of the contract.
If you want to sell the car instead of terminating, you need the leasing company’s consent. If the vehicle registration document carries code 178, the road traffic office will otherwise not issue a registration document to the buyer. More on this in the guide to the car sales contract.
Does the leasing company check my creditworthiness?
Yes, a commercial leasing company must do so before the contract. You are creditworthy if you can pay the instalments without touching the part of your income that cannot be seized, or if your assets secure the instalments. The basis of the check is stated in the contract.
That is what Art. 29 CCA on creditworthiness says. The part that cannot be seized is the subsistence minimum under debt enforcement law. If the leasing company requires insurance, such as fully comprehensive cover, that must also be in the contract (Art. 11 para. 2 CCA). If you cannot choose the insurer yourself, its costs are included.
How often is a used car offered with leasing?
Often. On a large car marketplace, 29 per cent of dealer listings mention the word leasing, that is 45’165 of 154’765 (as of 15.10.2026). On top of that, across the big Swiss marketplaces there are 980 listings in which someone wants to hand over their running lease to a successor.
Such a takeover only works with the leasing company’s consent. Before you agree, compare the instalment and residual value with what a car of this age is worth today. For comparison, also work out the figures for buying a used car.